How to Navigate Financial Hardship in New Zealand: A 2026 Guide to Debt Management Options and Relief Solutions
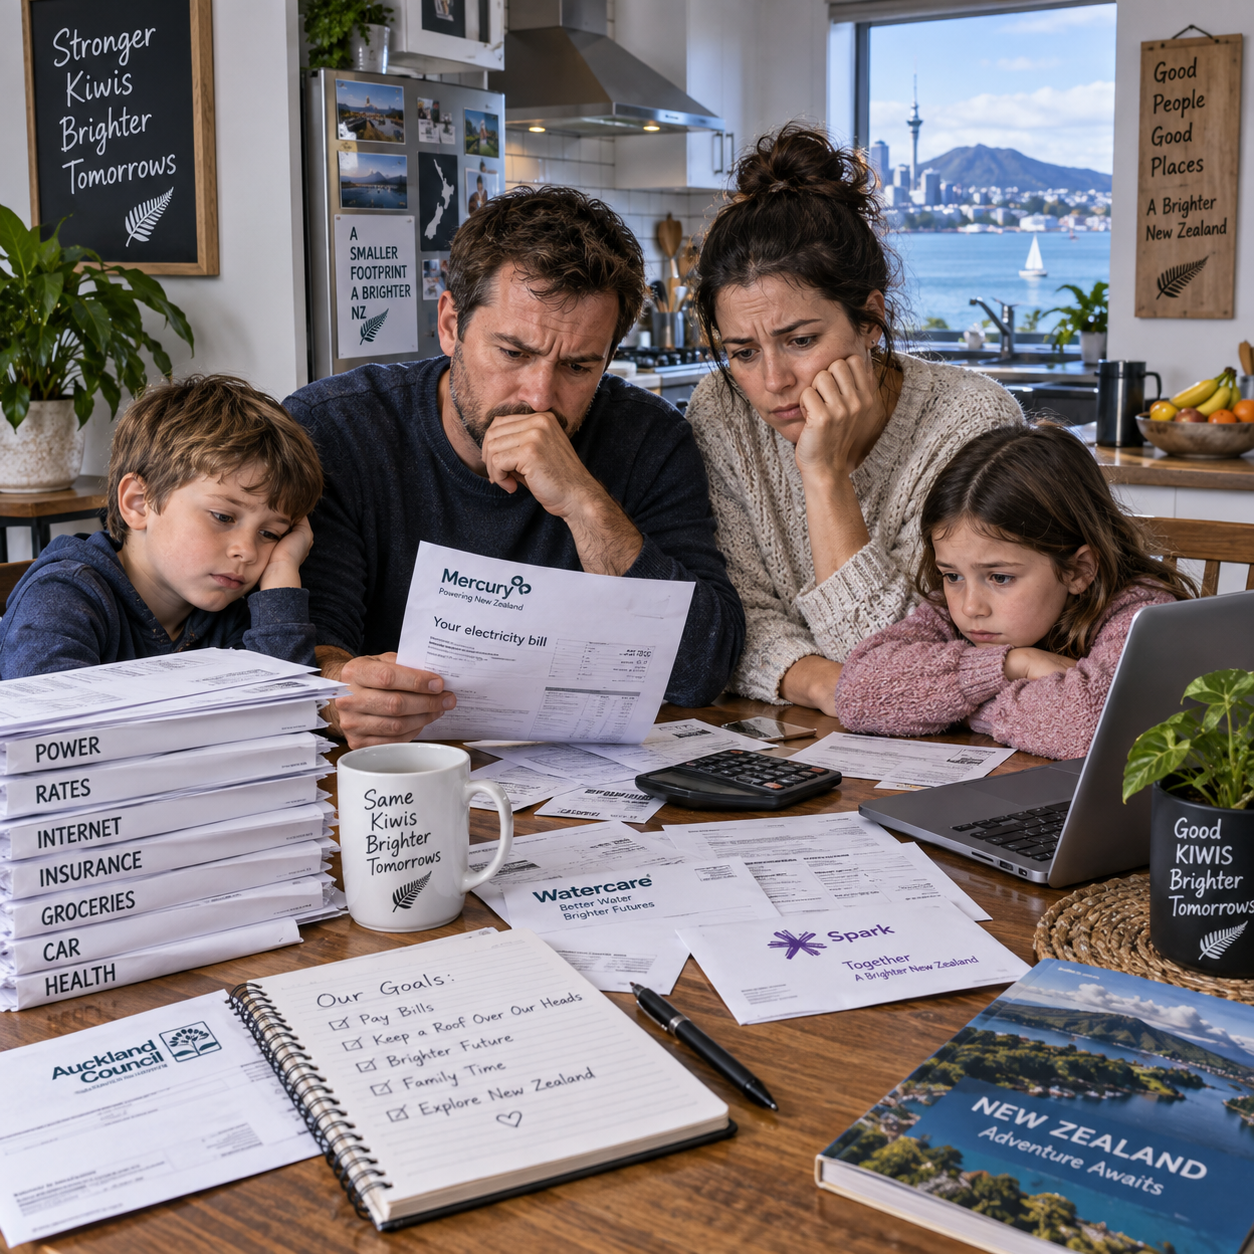
If you've been feeling squeezed lately, you're not imagining it. Between grocery prices that keep creeping up, rent that never seems to plateau, and mortgage repayments that jumped after fixed-rate terms expired, 2026 has been a genuinely tough year for a lot of Kiwi households. I've spoken with friends who never thought they'd struggle with money, and yet here they are, juggling due dates and dodging calls from collections agencies. The good news is that financial hardship in New Zealand isn't a dead end—it's a signal to pause, understand your options, and take deliberate action. This guide walks through how to recognise the warning signs, what debt management tools actually exist here, and how to choose a path that fits your specific situation without getting taken advantage of along the way.
Recognising the Signs of Financial Hardship
Financial hardship rarely announces itself with a single dramatic event. More often, it creeps in—a missed power bill here, a credit card used for groceries there, until suddenly you're paying more in interest than you can keep up with. Some telltale signs include consistently paying bills late, relying on buy-now-pay-later services or credit cards just to cover essentials, receiving overdue notices, or feeling that constant background hum of financial anxiety that follows you into everyday decisions.
Another red flag is when you're only making minimum payments and watching your balances barely move, or worse, grow. If you're borrowing from one source to pay another, that's usually a sign the situation has moved beyond a temporary cash flow hiccup and into something that needs a proper strategy.
Common Triggers in New Zealand's 2026 Economy
A few local factors have made this year particularly hard on household budgets. Many homeowners who locked in low mortgage rates a few years back are now rolling onto significantly higher rates, and that repricing shock has hit disposable income hard. Add to that persistent inflation on essentials—rent, electricity, insurance, and food—and it's easy to see why so many families feel like they're running just to stay in place.
The job market has also shifted, with some sectors tightening hiring and others seeing reduced hours rather than outright layoffs. That kind of underemployment is sneaky because it doesn't always show up in unemployment statistics, but it absolutely shows up in bank accounts. If several of these pressures are hitting you at once, it's worth taking that seriously rather than hoping things sort themselves out.
Understanding Your Debt Management Options in New Zealand
The good news is New Zealand has a reasonably well-developed system of support, ranging from free advice right through to formal legal processes. On the informal end, budgeting services and financial mentors—many accessible through MoneyTalks—can help you build a realistic budget, negotiate with creditors, and identify assistance you might be eligible for.
If your debt has grown beyond what budgeting alone can fix, debt consolidation loans are another common route, combining multiple debts into a single, hopefully lower-interest repayment. For more serious situations, New Zealand's Insolvency Act provides formal mechanisms including the No Asset Procedure (NAP), Debtor's Compromise, and bankruptcy—each designed for different levels of debt severity and different financial circumstances.
When to Consider Formal Insolvency Solutions
Formal insolvency isn't usually anyone's first choice, and it shouldn't be—but it exists for good reason. The No Asset Procedure, for instance, is designed for people with minimal assets and debts under a certain threshold who genuinely cannot repay what they owe. A Debtor's Compromise, on the other hand, allows you to negotiate a partial repayment plan with creditors that's legally binding once approved.
These options generally come into play once informal negotiation and budgeting adjustments have been exhausted, or when debt levels are simply too high relative to income for any realistic repayment plan. It's worth speaking to a financial mentor or insolvency practitioner before going down this road, since these processes carry long-term credit implications that shouldn't be entered into lightly.
Exploring Debt Relief Programs and Companies
Beyond New Zealand's domestic frameworks, there's also a broader industry of debt relief programs and companies, many of which operate internationally and offer services like debt settlement, negotiation with creditors, or structured repayment plans. These can sometimes be useful, but they vary enormously in quality, transparency, and cost.
Before signing up with any provider, it pays to do your homework. I'd recommend comparing options through resources like this breakdown of top debt relief programs & companies, which lets you weigh up features, credibility, and track records side by side. Doing this kind of research upfront can save you from committing to a program that charges high fees without delivering meaningful debt reduction.
How to Choose the Right Relief Solution for Your Situation
Choosing the right path really comes down to a few key factors: what type of debt you're carrying, how much you owe, how stable your income is, and what you want your financial life to look like in a few years. Secured debt, like a mortgage or car loan, behaves very differently from unsecured debt like credit cards or personal loans, and that distinction matters when deciding how to tackle it.
Broadly speaking, you're choosing between three tiers of intervention. DIY budgeting works well if your debt is manageable and your income is stable enough to make consistent progress. Professional debt management—through a financial mentor or consolidation—suits people with moderate debt who need structure and negotiation support. Formal insolvency is reserved for situations where debt has become genuinely unmanageable relative to income and assets.
Questions to Ask Before Committing to a Program
- What are the total fees, and how are they structured—upfront, ongoing, or success-based?
- How long will the program realistically take to complete?
- What impact will this have on my credit file, both during and after the program?
- Is this provider registered or compliant with New Zealand financial services regulations?
- What happens if I miss a payment partway through the program?
Any legitimate provider should answer these questions clearly and without pressure. If you're getting vague answers or a hard sell, that's a warning sign worth heeding.
Common Mistakes to Avoid When Dealing with Debt
One of the biggest mistakes I see is simply avoiding the problem—letting mail pile up unopened or ignoring calls, hoping things will improve on their own. Debt rarely fixes itself through inattention. Another common trap is taking on new debt to pay off existing debt, which can feel like relief in the short term but usually just delays and compounds the problem.
Be especially wary of unregulated 'quick fix' debt schemes promising to erase your debt overnight for a fee. These often target people at their most vulnerable and can leave you worse off. Lastly, many people jump straight to paid services without first exploring free, government-backed advice—which, in New Zealand, is genuinely high quality and often the smartest first step.
Free and Low-Cost Support Services in New Zealand
New Zealand has a solid network of support if you know where to look. MoneyTalks is a free helpline connecting you with financial mentors who can help build a budget and negotiate with creditors on your behalf. Citizens Advice Bureau offers general guidance and can point you toward the right specialist services for your situation.
If a dispute arises with a lender or financial provider, Financial Services Complaints Ltd (FSCL) offers a free, independent complaints process. And for those considering formal insolvency, the Insolvency and Trustee Service provides official guidance on NAP, bankruptcy, and Debtor's Compromise processes. Community-based budgeting services also exist in most regions, often through local councils or community organisations, and are worth searching out before turning to paid alternatives.
Financial hardship in New Zealand's 2026 economy is widespread, but it's not insurmountable. The key is recognising the signs early, understanding the full range of tools available—from free budgeting advice to formal insolvency—and doing careful research before committing to any paid program. Combine what's available locally with broader comparisons, including international debt relief options, so you're making decisions based on solid information rather than pressure or panic. With the right support and a clear plan, getting back on stable financial footing is absolutely achievable.